All companies, from one-person proprietorship to those employing hundreds of thousands of people, established firms or start-ups, are equally struggling in these trying times. One can surely, and perhaps effectively argue about the impact which may vary on a case to case basis, however generally speaking, the newer a company, the bigger the battle in front of it.
Startups are going through a tough time during this pandemic situation. India has the third highest number of startups next to U.S. and China. Quite obviously, the country is highly affected by the downturn of startups. Especially, during a time when the government has placed more emphasis in the development of startups for economic growth. But the Covid pandemic seem to thwart the plans of Government to nurture more startups for their economic growth. During this pandemic crisis, it is reported that most startups have failed, and only a few seem to be in the curve of progression.
Covid hampers Startups
Covid has had a devastating impact on almost every business in the world. The most affected industries include travel, hospitality and education among others. The social distancing behavior has restricted people from attending offices. These issues have caused the businesses to struggle in running their day to day operations. In many cases it is reported that the work productivity has been highly hit during the pandemic.
Although, many firms are managing through remote work, the effectiveness in terms of productivity, communication and collaborative work is a big question. Apart from it, many businesses are disrupted and new opportunities seem to arise. Experts estimate that the impact of Covid is believed to last for many months, and we can expect a recession hit economy for the next several years.
As per a nationwide survey on the ‘Impact of COVID-19 on Indian Start-ups’ conducted by Federation of Indian Chambers of Commerce and Industry (FICCI), jointly with the Indian Angel Network (IAN) with 250 start-ups, 70% of start-ups stated that their businesses have impacted by Covid-19. About 12% of the start-ups have shut operations and 60% are operating with disruptions.
The survey depicts that only 22% of the start-ups have cash reserves to meet the fixed cost expenses of their companies over the next 3-6 months.
The findings show that 68% of the start-ups are majorly cutting down their operational and administrative expenses.
Close to 30% of the companies stated that they will lay off employees if the lockdown was extended too long.
About 43% of the start-ups have already started salary cuts in the range of 20-40% over the period of April-June 2020.
On the investment front, 33% start-ups said that the investors have put the investment decision on hold and 10% stated that the deals have been called off.
Fragile nature of startups makes things worse
Startups in general are very fragile considering the constraints they operate in. Many startups may have very little funding to bootstrap their process. We understand how hard it takes for a startup to be successful under normal circumstances. Finding the right product fit for the market and acquiring customers are among the factors that determine the success and growth of a startup. The Corona pandemic makes it difficult for startups, since the world undergoes unpredictable changes and business is hard to get. The startups need more incubation and support during their initial years to be more productive in the future. These factors that make startups more fragile in nature make them vulnerable and difficult to survive.
In this Corona pandemic situation, the startup firms are affected badly. It is believed that about 90% of the startups have failed in India. There is another report that the startups have cash reserves to last only for the next 3 months. These are bad news for the startups in our economy. The fragile nature of startups and the inexperience of entrepreneurs can very well be the cause for such failures.
A quarter of India’s startups would be in serious trouble if adverse consequences of the COVID-19 pandemic persist for long, according to information technology industry veteran Senapathy (Kris) Gopalakrishnan. “There will be more failures, unless they get additional funding from existing investors or support from banks on working capital or support from government for some form of debt or grants. We will see more companies get hurt as this prolongs,” said the Chairman of early stage startup accelerator and venture fund, Axilor Ventures.
A comparison of priority investment sectors pre and during COVID-19 shows that 35% of the investors are now looking at investments in healthcare start-ups, followed by EdTech, AI/Deep Tech, FinTech and Agri. Meanwhile, 44% of the incubators surveyed highlighted that their day-to-day operations have been considerably impacted by the COVID-19.
How should startups respond to the Corona crisis
However, there is a silver-lining amidst all the gloom of Corona pandemic. We will take a look at some of the brave startups who have looked up-to new opportunities for growth. Indian startups have ground-breaking ideas and are hard-working people, and success is just around the corner. A few startups are adapting to the present situation and meeting the needs of current market conditions. These are certain aspects that can help startups to survive during the pandemic.
New Opportunities Arise amidst Corona
It is time for startups to look beyond the ordinary to be successful. Relying on traditional mode of business may not yield good results. That may be the reason for failure of many startups. Successful startups have capitalized on the new opportunities that are presenting itself in the society. To make this understand better, people are looking for safety during this time, and providing ways for safe products and services can help startups to stay afloat. Startups should keep looking for those new opportunities that are opening up, and make plans to meet those opportunities. After all this is not the end of the world and keeping your company alive for the next several months can be crucial for their success in the long run.
Rapid Innovation
Rapid innovation is another startup thing that’s caught the eye of business community. Think of startups like Uber, Airbnb and many others, they all brought an innovative idea to the table. The world is a different place because of these firms. These rapid innovative ideas are the prime reason for the success of these next generation technology firms. They saw a unique need in the society and countered it with smart tech solutions that solved people’s problems. Uber has solved the cab problem in providing a hassle-free cab riding experience in the city. Take Aribnb, they provide an innovative concept in accommodating people in shared spaces, which is a big hit and has grown to become a multi-million dollar company. Likewise, many startups today are coming with rapid innovation ideas to fight the Corona pandemic. It is a noble effort by the startups to endeavor in such activities through their ideas and technology. I personally know of an Artificial Intelligence startup that lends its AI search technology for free to the medical community to find vaccine for Corona. The AI start up firm found their technology suitable for medical research community and tailor made their AI product to be useful for medical research purpose.
Government initiative to sustain Startups
The Government has a huge role to play to support startup firms in this pandemic. The Indian government has come up with many initiatives to support startups in the country. The business community can take advantage of these government initiatives and make the best out of it. The government has announced new plans to mentor startups, regulatory reforms in favor of startups, funding sources and investor engagement facility to name a few. It is indeed difficult for startups to survive without favorable government initiatives. It is imperative that Government looks keenly into the affairs of startup development and does the needful. These initiatives can meet the financial deficit of startups. The mentorship programs provided by the Government can be handy to get business insights for experienced campaigners. They can provide valuable advice to steer the startups in the right direction nullifying the Covid impact.
Stakeholder support is essential for Startup growth
The support of stakeholder can go a long way in sustaining the Startups. During these tough times, sometimes startups may need additional funding or much needed morale boost from the stakeholders. It is vital for Stakeholder to have confidence on the ambitions of startups. These are little things that can fetch a long distance. Encourage and support from the stakeholder can keep the morale of the team to achieve their goals.
Success stories of Startups and coping mechanism
Some startups are doing a great job in adapting to the present circumstance. For instance, Zomato has been hit badly as customers have grown skeptical about buying food online. The firm went ahead to establish measures to comfort its clients about the safety of their food, and found a vast opportunity. Zomato has made good business strategic moves in finding big opportunities opposed to smaller ones to be able to survive. They have founded a new segment called Zomato Market where groceries are delivered to home residents, which adds great value to customers during this pandemic. The success of the Zomato Market has led them to launch their extended service in countries like UAE and Lebanon. In an interesting equation, Zomato is ready to deliver alcohol to home residents.
While the travel industry has taken a heavy beating, firms like MakeMyTrip have to be on the edge to add tremendous value to the present scenario to stay afloat. In a strategic move, MakeMyTrip realized the present travel equation and is offering a platform for short stays for their customers. They have piloted a short stay program for travelers wanting to visit Tirupathi in collaboration with Goibibo and Redbus. MakeMyTrip is keen to provide a great experience for its customers even during this pandemic situation, and their co-branded cards with leading banks like ICICI provide a rewarding travel experience.
A popular gym and fitness joint called Curefit in the country has succumbed to the pressures of Covid. The firm has taken to online classes to keep their gym facility running. They have created a subscription model, so the fitness enthusiasts can still keep the ball rolling and maintain their perfect physique. The virtual classes will help them to stay connected with their instructors, and continue their exercise routine.
What we can perceive from these interesting stories is there are ways to keep a business going. Zomato, Makemytrip and Curefit are good examples on how startups are coping during this pandemic. The entrepreneurs who have put their thinking cap on to assess the situation and do the right thing have found the big advantage.
It is tough, but not impossible
Startups can leverage the government support, policies, stakeholder support, rapid innovation to come successfully out of this Covid crisis. It can be tough, but it is not impossible. We should appreciate the noble efforts of some startups who have geared up in fighting the Corona spread. Seeing the new opportunities and adapting to the disruptive world is key to surviving in this pandemic. Taking the right initiatives at the right time and having the belief to succeed will help startups to see through this massive storm.
“Startups must use their strengths in innovation to re-strategize and re-think their business,” said Ganesh Raju, Co-Chair, FICCI Start-up Committee and Founder, TurboStart.
]]>

Launching satellites in to space has always been a dream endeavor. A source of national pride as well as pinnacle of decades of human engineering, space journeys are nothing short of miracles. Ever since humans took to flying, nations have attempted to conquer the space and been in a race to launch new satellites, both looking inwards towards the Earth and those looking outwards towards the vast and immeasurable expanse of unknown Space. The space race has heated up with each breakthrough in technology and has transformed from monolithic government enterprises to an agile and cutting-edge private domain.
Since the start of the first space race, a cold-war era much celebrated source of national pride, countries have launched nearly 8,400 satellites in to space, of which roughly 2,800 are still in operation (data compiled through various sources, see here and here). According to Statista, of the 2,666 active artificial satellites orbiting the Earth as of March 31, 2020, 1,327 belong to the United States. This is by far the largest number of any single country, with their nearest competitor, China, accounting for only 363. During the last decade however, the space race has largely transformed to a private sector endeavor, with SpaceX transforming the dimensions of everything about launching satellites. The last two decades have been the most promising from the perspective of advancement in technology, as well as the advent of micro usage of satellites. The focus of the satellite launch missions is shifting away from traditional large satellites towards small satellites. Broadly speaking, there are 9 different kinds of satellites launched in to Space, depending on their function and the distance from Earth these satellites operate from. There are nine different types of satellites i.e. Communications Satellite, Remote Sensing Satellite, Navigation Satellite, LEO, MEO, HEO, GPS, GEOs, Drone Satellite, Ground Satellite, Polar Satellite.
During the 1950s and 60s important work like Orbital Radio Relay by American engineers John Pierce of American Telephone and Telegraph Company’s (AT&T’s) Bell Laboratories and spin-stabilization technology that provided stability to satellites orbiting in space by Harold Rosen of Hughes Aircraft Company helped in making commercial communication satellites possible. When the U.S. National Aeronautics and Space Administration (NASA) was established in 1958, it embarked on a program to develop satellite technology. Soon, this work was followed by Telstar1, launched on top of a Thor-Delta rocket on July 10, 1962, which successfully relayed through space the first television pictures, telephone calls, and telegraph images, and provided the first live transatlantic television feed followed by Telstar 2 which was launched May 7, 1963. Telstar1 transmitted the first phone call via satellite—a brief call from AT&T chairman Frederick Kappel transmitted from the ground station in Andover, Maine, to U.S. Pres. Lyndon Johnson in Washington, D.C. Following the success of Telstar, NASA soon started an experimental spacecraft program for active geosynchronous communication satellites, known as Syncom, all of which were developed and manufactured by Hughes Space and Communications. Syncom 2, launched in 1963, was the world’s first geosynchronous communications satellite. Syncom 3, launched in 1964, was the world’s first geostationary satellite.
One of the foremost and earliest uses of Satellites has been to create a blanket around the Earth to establish seamless and fast communication. According to Britannica, the idea of communicating through a satellite first appeared in the short story titled “The Brick Moon,” written by the American clergyman and author Edward Everett Hale and published in The Atlantic Monthly in 1869–70. The story describes the construction and launch into Earth orbit of a satellite 200 feet (60 metres) in diameter and made of bricks. The brick moon aided mariners in navigation, as people sent Morse code signals back to Earth by jumping up and down on the satellite’s surface. The first practical concept of satellite communication was proposed by 27-year-old Royal Air Force officer Arthur C. Clarke in a paper titled “Extra-Terrestrial Relays: Can Rocket Stations Give World-wide Radio Coverage?” published in the October 1945 issue of Wireless World. Clarke, who would later become an accomplished science fiction writer, proposed that a satellite at an altitude of 35,786 km (22,236 miles) above Earth’s surface would be moving at the same speed as Earth’s rotation. At this altitude the satellite would remain in a fixed position relative to a point on Earth. This orbit, now called a “geostationary orbit,” is ideal for satellite communications, since an antenna on the ground can be pointed to a satellite 24 hours a day without having to track its position. Clarke calculated in his paper that three satellites spaced equidistantly in geostationary orbit would be able to provide radio coverage that would be almost worldwide with the sole exception of some of the polar regions.
Telecommunications satellite are Earth-orbiting system capable of receiving a signal (e.g., data, voice, TV) and relaying it back to the ground. Communications satellites have been a significant part of domestic and global communications since the 1970s. The use of satellite communication in telecommunications pertains essentially to the use of artificial satellites to provide communication links between various points on Earth. Satellite communications play a vital role in the global telecommunications system. Approximately 2,500 artificial satellites orbiting Earth relay analog and digital signals carrying voice, video, and data to and from one or many locations worldwide.
LEO, Low Earth Orbit, and MEO, Medium Earth Orbit, satellites come under the category of non-geostationary-orbit (NGSO) satellites. LEO satellites orbit at an altitude below 1,243 miles above mean sea level, while MEO satellites orbit in the region between LEO and GEO (geostationary) satellites – between 1,243 – 22,245 miles. Geostationary Satellite is an earth-orbiting satellite, placed at an altitude of approximately 22,300 miles (35,800 kilometers) directly over the equator, that revolves in the same direction the earth rotates (west to east). At this altitude, one orbit takes 24 hours, the same length of time as the earth requires to rotate once on its axis. LEOs or Low Earth Orbit satellites are being increasingly used in space since the 1990s. In the last decade, rapid advances in camera technology and computer miniaturization have allowed for reduction in payloads using advanced optical imaging or radar observations which in turn led to smaller and smaller satellites.
Image Source: Wikipedia
Furthermore, advances in technology have introduced many novel concepts that have revolutionized the race to launch satellites. First of these technological advances is that of re-use of hardware, a hitherto unheard of phenomena that has taken the entire satellite industry by storm and has now become the de-facto inspirational standard. While previous space missions did offer some re-usability, Falcon Heavy was the first to offer reusable launch vehicles, i.e. the hardware used to launch the actual space shuttle or satellites or other payload. The rocket boosters used on these missions now have a controlled and breathtakingly simultaneous landing onto the launch pad. This recovery massively reduces the launch cost for both exploration and scientific discovery. The Falcon Heavy has been promoted as providing a cost of roughly US$1,300 per kg of payload, while the space shuttle cost approximately US$60,000 per kg. Secondly, instead of producing a bunch of different engines with a bunch of different horsepower ratings, satellite launch companies are now focused on having just one first-stage engine, the Merlin. The more powerful a rocket has to be, the more first stage rockets, or Merlins in case of SpaceX, are bundled into its first stage. SpaceX’s initial test rockets flew on just one Merlin. The workhorse of the SpaceX fleet, Falcon 9 which used a single cluster comprised of nine engines, as implied by its name. The Falcon Heavy uses three of those clusters, utilizing 27 first stage engines in total. This fades in comparison to the Saturn V’s five, the SLS’s four and the Delta IV’s three. The Atlas V, which can be configured with different numbers of first stage engines, maxes out at six. Of course with the increase of multi-engine use, risk has increased of any one of them breaking down or blowing up and jeopardizing the whole mission, or in the worst case scenario, destroying the whole space ship and its payload and causing loss of human life. However, advances in technology and increased scientific knowledge on aerodynamics concepts and safety measures mean that actual chances of any untoward incident are minimal.
Companies ranging from OneWeb to SpaceX and Planet have been deploying large fleets of satellites (fleets that could eventually include thousands of individual satellites) for applications ranging from telecommunications to Earth observation. One of the reasons why the LEO sector has become a hotbed of investment in recent years is that space has become more commercially accessible. Launch costs which historically were prohibitive, have come down dramatically, particularly since SpaceX started an Uber-pool style service last year that allows small satellites to hitch a ride on its Falcon 9 rocket. The company’s ride-share program launches satellites into orbit for as little as US$1-million for 220 kilograms, according to Space X’s website. More than profit margins however, SpaceX should be identified with the disruption it is leading in the global space industry as we saw previously with SpaceX’s path breaking innovation of reusable hardware and simplistic design concepts.

Image Source: Starlink
Depending on the specific use, amount of latency expected and conditions of operations, LEO, Low Earth Orbit, and MEO, Medium Earth Orbit, and Geostationary satellites are deployed. Owing to their higher operating altitudes, geostationary satellites tend to gravitate towards higher latency with less spatial resolution of data when compared with non-geostationary orbit satellites or NGSO . However, in a maritime context for example, a delay of milliseconds has little impact upon the transmission of certain applications, eg, ship condition reports and live engine data. And for land stations, the main advantage of GEO satellites is that they are always in the same position relative to the earth, meaning that antennas require no reorientation. Coming to non-geostationary orbit satellites or NGSO, one of the main advantages of NGSO satellites over GEO satellites is considerably lower latency. Due to the operating distance over earth, GEO satellites have roughly 550 milliseconds of round-trip latency time, while LEO satellites boast a latency of 240 milliseconds, providing a distinct and significant advantage in the cutting age of real-time applications. For example, the combination of high bandwidth and low latency is a highly-prized aid in the implementation of telecommunications, videoconferencing, and so on.
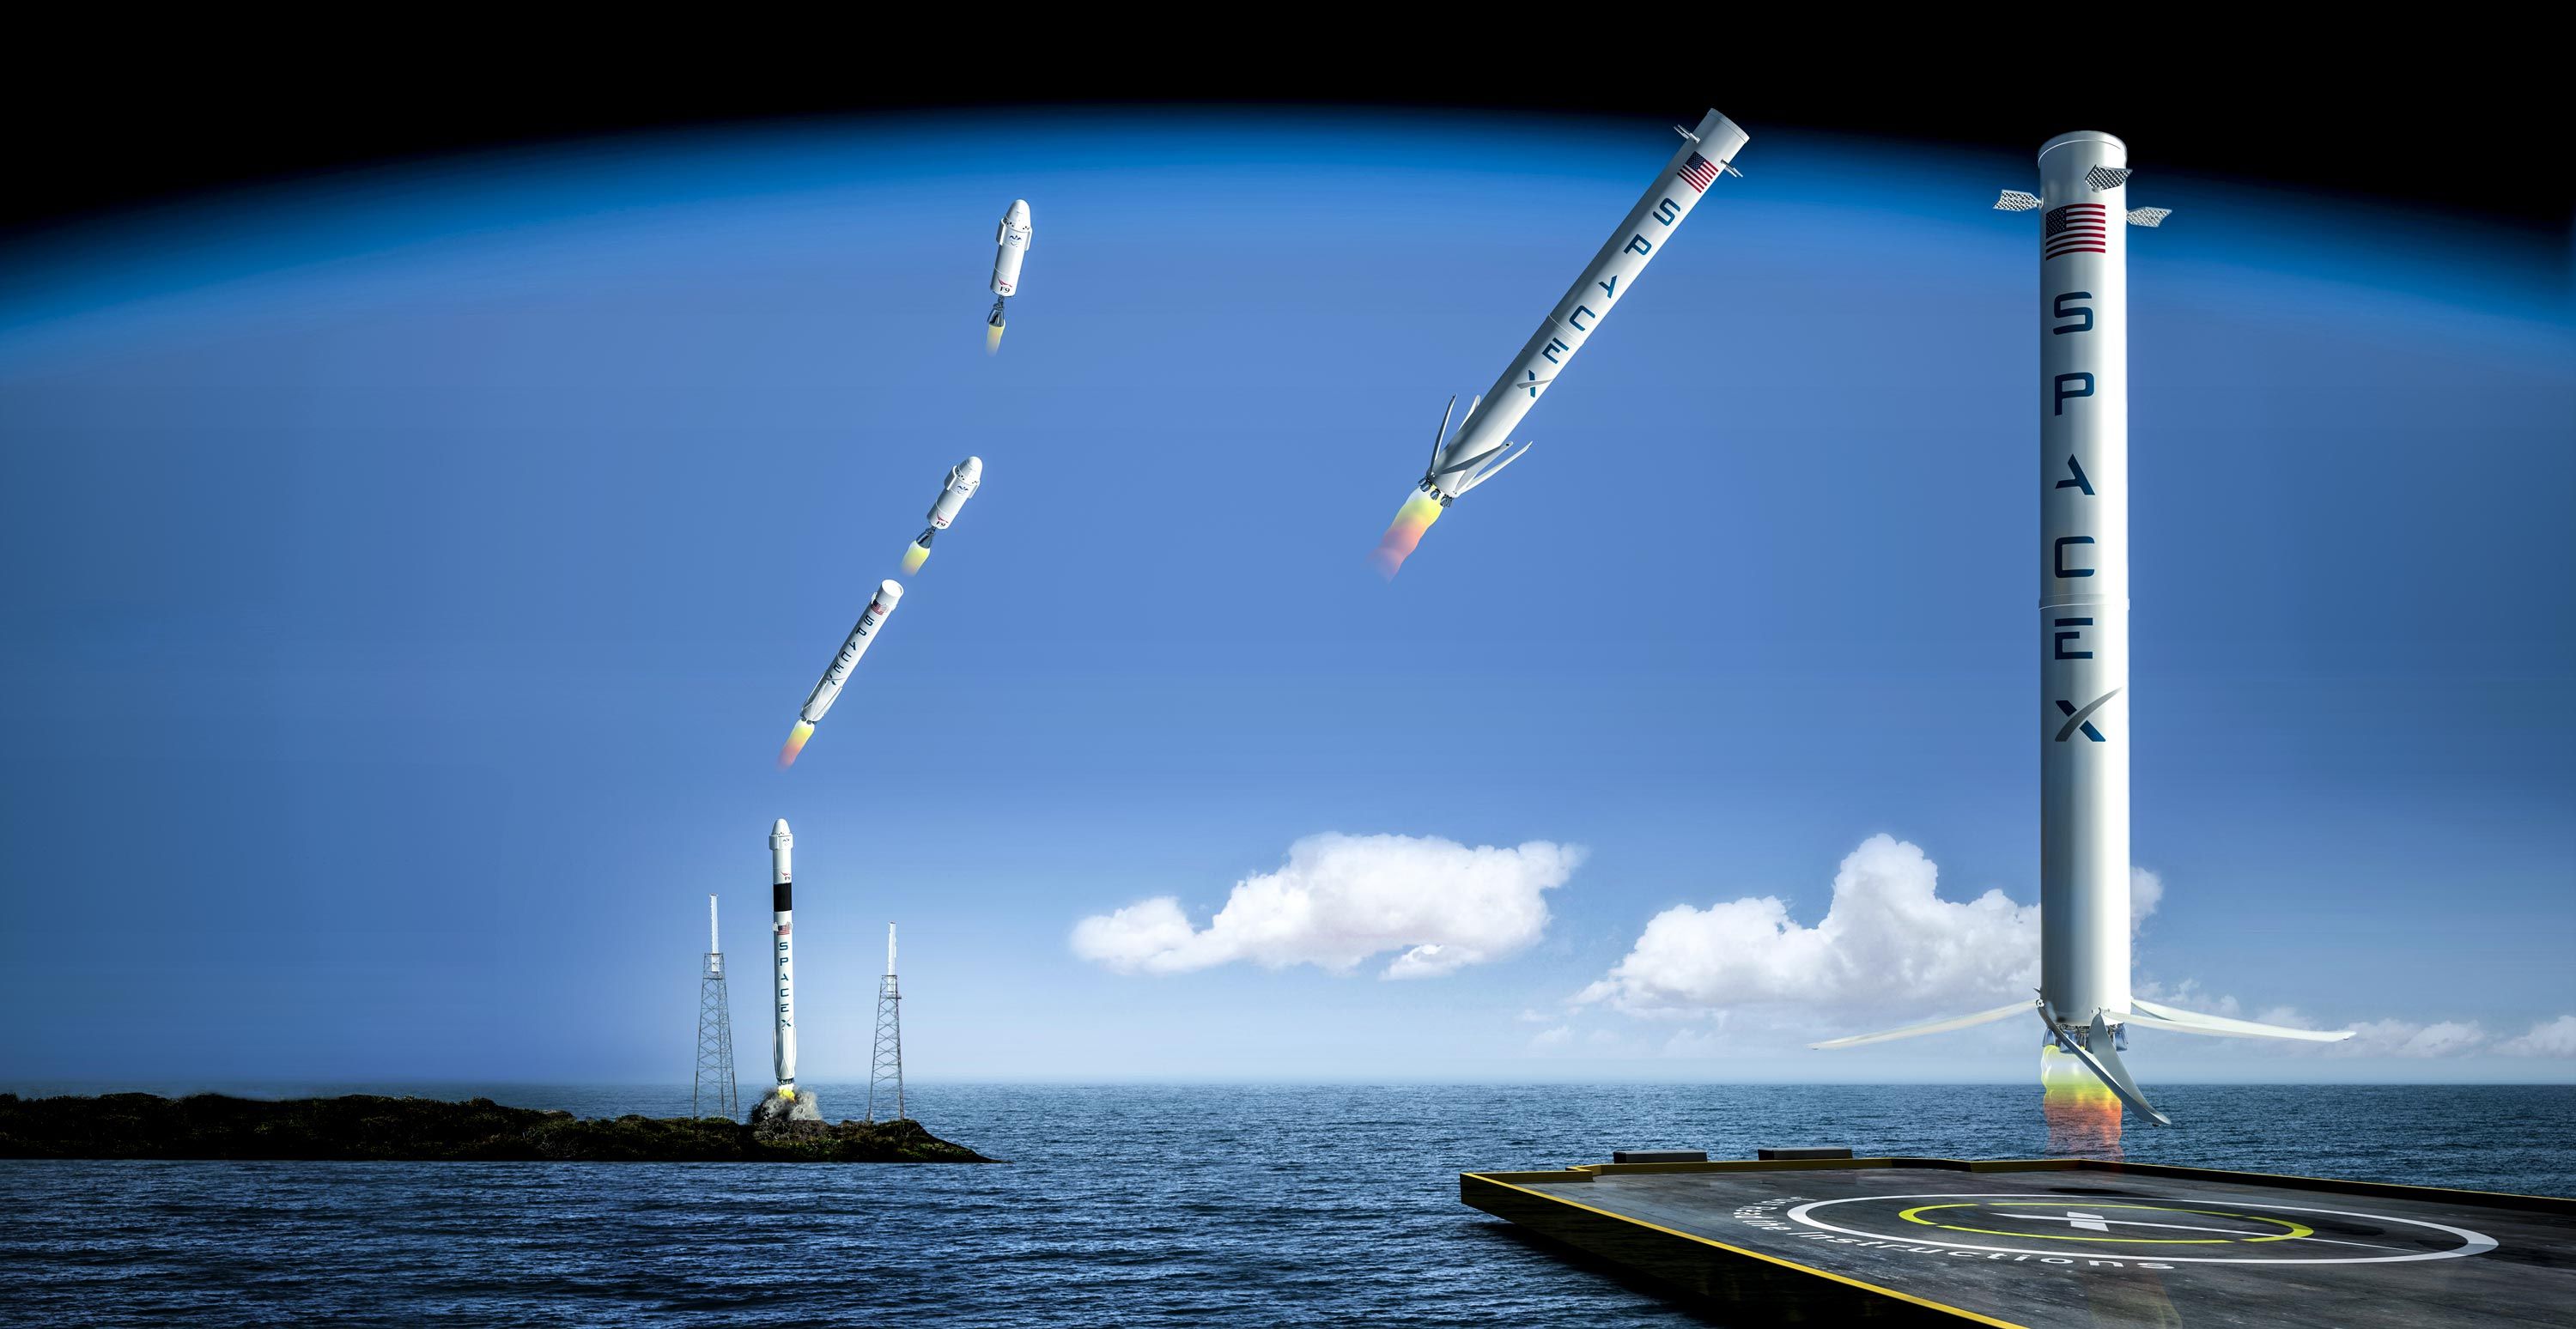
Image Source: Popular Mechanics
In the recent years since the advent of Tesla’s SpaceX and its path-breaking new generation of rockets which offer re-use capabilities the space race has heated up attracting billions of dollars in investments and interests from the best and biggest organizations. Amazon’s project Kuiper recently got the green light from the U.S. Federal Communications Commission last month for a 3,236-satellite constellation, just as London-based OneWeb has emerged from bankruptcy proceedings with US$1-billion in fresh capital to restart its own project. Ottawa-based Telesat, meanwhile, has locked down spectrum – the radio frequencies used to transmit wireless signals – and secured millions in funding from the federal government as it looks to deploy a smaller, more efficient constellation of nearly 300 LEO satellites. SpaceX’s application for a Basic International Telecommunications Services licence in Canada garnered a number of supportive submissions to the regulator. More than 2,000 parties submitted responses to the Canadian Radio-television and Telecommunications Commission’s website, many of them from rural households and businesses cheering the initiative. Their plan is to offer high-end internet coverage for clients like governments, mining companies and shipping conglomerates, as well as extending internet coverage to regions too remote or too poor to make use of conventional ground based internet. As regards the future of satellite communications, network providers are looking towards the integration of new LEO and MEO solutions with existing, tried-and-tested GEO services so as to provide the most productive and cost-effective amalgamation of coverage and bandwidth usage.
OneWeb, recorded an average latency of 32 milliseconds in July 2019 on transmissions between space and South Korea. Musk, the founder of Space Exploration Technologies Corp., has said that his Starlink satellite system is aiming for a latency of 20 milliseconds initially, which he further hopes to cut in half gradually. By contrast, geostationary orbit systems have a median latency of nearly 600 milliseconds for a round trip.
With the growing digital divide fueled by lagging investment in rural communications infrastructure, which is exacerbated further by the COVID-19 pandemic, the opportunity is ripe for new age solutions providers to move in. Billions of dollars are pouring in to satisfy the world’s insatiable appetite for bandwidth, particularly in far-flung regions where laying fibre-optic cables is prohibitively expensive. The need to stay connected has moved workplaces, schools and even health care services online, further highlighting the digital divide between users who have access to affordable, high-speed internet and those who don’t. For the average user that relies on fast internet speeds for business, education and more, download speeds of 50 Mbps and upload speeds of 10 Mbps are required as the bare minimum to participate in those activities, while most users in rural areas actually get a fraction of that.
In a related development not so long ago, the Federation of Northern Ontario Municipalities (FONOM) and other Northern Ontario stakeholders has turned its attention skyward calling for better access to high-speed internet with the Municipal advocacy group calling on the Canadian government to allow Musk’s Starlink an operating licence. The announcement follows the passing of a resolution at its recent board meeting. FONOM, which represents 100 communities in northeastern Ontario, works to better municipal government in Northern Ontario and improve legislation respecting local government in the North.
Numerous government bodies, at local, state and national or Federal levels have expressed interest in public-private partnerships with the dual aim of providing connectivity to far-flung and difficult to reach areas, while also aiming to use private enterprise to speed up breakthroughs in the field of satellite communications.
The Canadian government has made investments in improving rural and remote broadband internet including funding to Telesat who want to build a satellite constellation in Low Earth Orbit (LEO) and has agreed to spend up to 600 million Canadian dollars ($456.6 million) more on capacity.
If Musk has his way, by 2025 no less than 11,943 of his satellites will circle the Earth, and if permission is granted, the ultimate result would be a staggering 42,000. SpaceX is planning to beam broadband directly to consumers; each home will be outfitted with a half-metre-wide circular antenna resembling a UFO on a stick. Telesat, meanwhile, is focused on enterprise clients such as the aerospace and maritime industries. It also plans to provide “backhaul” connectivity to telecom companies, which will then transmit the signal to customers’ homes via ground-based networks. Amazon is aiming for a mix of residential customers and telecom carriers. For its part, the telecom companies do not view LEO companies as competitors, analysts say, because the new satellite providers are focused on areas where it’s impractical to build networks of fibre-optic cables.

Image Source: Cnet
According to Lluc Palerm, a senior analyst at consultancy firm Northern Sky Research, the LEO industry is projected to expand as global demand for connectivity grows. Today, satellite communications generates about US$10-billion to US$15-billion in revenue annually, comprising about 1 per cent of the telecommunications market. That could grow to as much as 5 per cent of overall telecom industry revenues, Mr. Palerm says. Mr. Musk has said he believes the revenue opportunity for SpaceX’s Starlink constellation is around US$30-billion.
As satellites get smaller, they are getting easier to build and launch. All this may sound music to some ears, but for a section of experts, this is worrisome.
While neither Low Earth Orbit Satellites nor the use of Satellites for communication are new concepts, what is different is the sheer scale of recent proposals, with the big firms planning to launch satellites in the thousands. The new ventures are counting on savings from smaller, cheaper satellites and reusable rockets, along with more powerful software capable of tracking all those hand-offs.
But the costs of building LEO constellations are astronomical and technological hurdles remain. While LEO satellites operating in constellations, or groups of tens or hundreds of satellites, promise to solve the burning issue of latency encountered with the existing fleet of geostationary (GEO) satellites, they also come with a much higher price tag. According to Telesat, In the world of telecommunications, LEO satellites which orbit the planet in a constellation formation, enable download speeds that are eight times faster than traditional satellite systems and on par with those offered by fibre-optic cable.
The high cost of LEO satellites owes to a mixture of high manufacturing and high operating costs. A typical communications satellite costs as much as US$60,000 a kilogram and with average weight around 300 to 400 kilograms for each satellite, and the need to operate in a group of satellites, the cost quickly climbs up. As Low Earth Orbit LEO and Medium Earth Orbit MEO satellites do not synchronise with the Earth’s rotation and orbit the earth more rapidly than GEO satellites – an orbital period of 128 minutes or less for LEO, and an average of between 2 and 8 hours for MEO – multiple satellites are required in order to achieve seamless coverage.
In addition, the primary difference between Geostationary satellites and LEOs is the need to have antennas which are constantly moving as the LEO satellite constellation moves meaning that ground equipment for LEO systems is much pricier. LEOs require electronically steerable antennas which are capable of tracking multiple satellites passing overhead at the same time across the sky. These antennas are more expensive, posing a challenge to SpaceX’s and other operators’ plans to target the consumer market.
Previous attempts to create these near Earth constellations of satellites operating in Low Earth Orbits have been met with lot of skepticism, fading interest from investors and scaling down of initial plans owing to commercial non-viability. The most notorious example of these is Iridium, a constellation of 66 satellites built by Motorola in the late 1990s that was rescued from the verge of collapse by a group of investors led by a former airline executive. The company had to drastically scale back its plans, restructure and shift gears to providing emergency communications. Iridium’s LEO constellation is one of a small handful of such systems currently in operation, generally focused on the enterprise market. More recently, British-based OneWeb filed for Chapter 11 restructuring in March after its backer, Japan’s SoftBank, declined to put up fresh capital. The company had put 74 of its planned 648 satellites into orbit before seeking bankruptcy protection, but has since found new owners – the British government and Indian telecom company Bharti Enterprises.
Further, on the technical side, many analysts caution that the potential market may not be large or lucrative enough for LEO companies to recoup their sizable investments. The U.S. telecom regulator FCC, said in a report it doubts satellite operators will be able to keep latency under 100 milliseconds, even with low-orbit satellites. That means SpaceX and other LEO companies could have a tough time getting access to an FCC fund aimed at supporting rural broadband projects. Analysts also doubt the commercial viability citing the low incomes in rural areas.
The low Earth orbit region is already heavily used by scientific, remote-sensing and telecom satellites as well as the International Space Station (ISS). A large scale increase in the number of satellites would increase the risk of space collisions and the ensuing multiplication of debris — in the worst-case scenario, it could render the LEO and near-space environment unusable.
]]>
A look at how Regulators, Companies and Individuals are shaping the Broadband map across America
Technology and the needs of businesses and consumers continue to evolve. Over the last 2 decades of mass internet penetration, availability and affordability have become the two key cornerstones of any efforts to shape internet policy, whether its at a regulatory level, like FCC or representatives of state broadband programs or at an internet service provider company level, like AT&T, Verizon.
Broadly speaking, according to FCC definition, Broadband is defined as reliable high-speed internet, having download speeds of at least 25 megabits per second (Mbps) and upload speeds of at least 3 Mbps. Broadband internet may be delivered via multiple technologies, including Fiber broadband, fixed wireless, digital subscriber line (DSL), or Cable broadband. Each technology has varying costs of setup and maintenance, with cable being generally regarded as the most cost-effective though technologically limited solution.
Perhaps more so than any other technological innovation in human history, the Internet has changed our daily lives in significant and permanent ways. Among many other things, the transformation has occurred faster than any other adaption of technological changes. Over the space of 2 decades, home broadband adoption has grown from 3% of all American adults age 18 and older to almost 80%. By comparison, it took telephone to nearly 8 decades and electricity more than 30 years to reach the same level of penetration, despite deals .
Broadband is increasingly intertwined with the daily functions of modern life. It is transforming education, social services, healthcare, agriculture, supporting economic development initiatives, and is a critical piece of efforts to improve human life and socio-economic factors of human development.
Broadband has become the quintessential communication essential in the digital age and the era of Internet. Literally and figuratively, everything is available on the internet. And being connected, being connected always, has become an objective, an input and a goal statement in and of itself. Everyone, everywhere, has some purpose which requires them to access internet resources, unless of course, people making the active choice of living off the grid. However, with more than 19 million disconnected households across the country at the most conservative level of estimate, it is impossible to capitalize on broadband’s full economic and social impacts. While a presidential platform can incentive policy reform at the federal level, the road to change is still a long one, slowed by political infighting and congressional discord.
Internet Availability and Affordability for everyone
When people refer to broadband, most are referring to interrelated, sometimes overlapping characteristics of the sector. These two characteristics are like two sides of the same coin, and in every facet are tied to each other. The first is the digital telecommunications backbone or the infrastructure, whether wireless like mobile or wired technologies like Cable, DSL, etc, that enables outreach and availability of high-speed transmission of data. This digital backbone and physical infrastructure is both capital-intensive and technology-intensive, as in the front-end infrastructure, the towers, the wire lines, the cables, the physical buildings and exchanges and offices where the telecommunication equipment is assembled requires significant up-front monetary investment as well as time, whereas set-up of back-end technology and processes to enable the operations, billing and provisioning of broadband services requires years of preparation. The other side of this coin, the federalist and state policy frameworks that govern physical infrastructure and related coverage especially in areas with limited revenue and growth potential, dictate how the implementations are carried out. Though broadband’s antiquated definition tends to focus strictly on the transfer speeds and the network capabilities of the underlying technology, iin reality, broadband infrastructure can only reach its potential if every individual can use the service, and if policy frameworks are in place to support ubiquitous, near barrier-less adoption.
By pricing the broadband service, especially the entry levels prohibitively high so that its out of reach of certain section of the society, or by excluding the geographical areas or communities altogether, or by not investing or reducing the investment in upgrade and maintenance of the lines, it is certainly true that in certain parts of the country the entry barriers to obtain sufficiently fast broadband connection are too high. And lastly, not having adequate competition at a market level not only forces the customers to settle for low standards of service, but stifles innovation and investment, two most critical factors for market growth.
There are three primary areas within the colloquial term broadband availability that must be broken down for an effective analysis. These are availability of service, affordability of services and the presence or lack of competition, as in, the competition exerted by each internet service provider competing for market share. Lets look at these briefly.
- Availability of Service -: this is apparently self-explanatory and generally the first step of internet connectivity. This is plan and simple availability of broadband signal in an area. According to the most recent data available, the Federal Communications Commission (FCC) estimates that 21 million Americans still lack broadband access according to the most recent data available. Many researchers have however cast serious aspersions on the veracity of this data, at times placing the number of people without access to reasonable internet as high as 162 million.
- Availability of speed tiers and plans and Affordability -: FCC voted in January 2020 to approve a $20.4 billion Rural Digital Opportunity Fund that will make grants to broadband providers to build broadband networks where there is currently no or substandard service, however the money will be disbursed without any guarantee that the grant recipients will help to make broadband more affordable for low-income customers. It is strongly believed that to avoid corruption and to prevent this from becoming yet-another-failed scheme, Congress and the FCC should require, as a condition for funding this broadband deployment, true high-speed service at actually affordable prices—for instance, service rated at 50 Mbps for upload and download with unlimited usage for $10 per month to eligible recipients. What is alarming is that home broadband adoption rates aren’t improving. Approximately 73% of U.S adults use broadband service at home, but that figure has remained stable for the past three years. Too many people aren’t subscribing to broadband even when it is available to them. Affordable service is crucial.
- Lack of more than one service provider -: According to a Fortune Article, laws in 19 states restrict local communities from experimenting to increase broadband deployment. These laws should be revisited and repealed. An indubitable truth – when new competition is introduced in broadband markets, the benefits are demonstrable. Look no further than Kansas City, Kan.; Chattanooga, Tenn.; Wilson, N.C.; and Longmont, Colo. for evidence that competition from private or municipal broadband provider results in incumbent providers dropping prices and increasing speeds — benefits which can not be realized with any amount of coaxing or appeals as seen in nearby areas where old standards still persisted in a market without competition. An estimated 35% of people have only 1 choice of broadband provider; another 37% have just two to choose from. Without competition, people—especially those with lower incomes or those who live in rural areas—are threatened with artificially high prices, lower-quality service, and little innovation. A Wall Street Journal report published last year found that low-income areas and high-income areas pay similar median monthly costs (about $66) for stand-alone internet, but poorer areas get 40% slower speeds for the price.
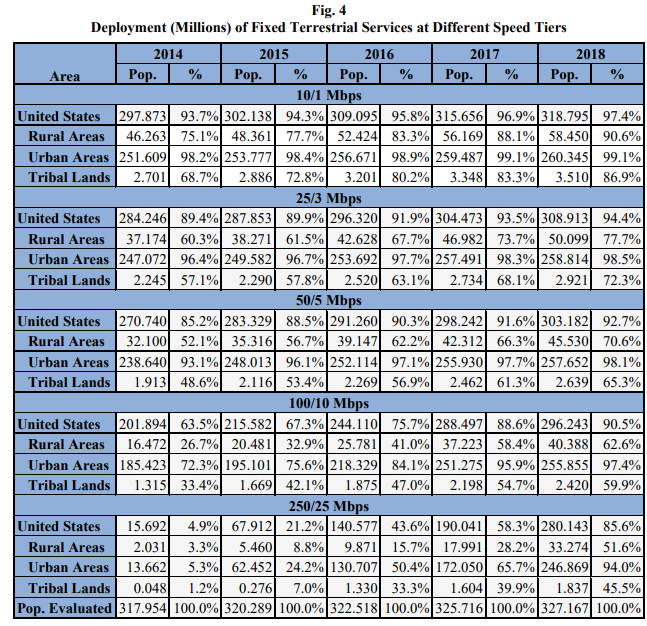
Image: Figure 4 FCC report
Figure 4 shows deployment of fixed terrestrial services at various speed tiers from year end 2014 through 2018.132 As of December 2018, fixed terrestrial service of 50/5 Mbps service is deployed to 92.7% of the population, up from 91.6% in 2017. Between 2017 and 2018, the deployment
of 100/10 Mbps increased from 88.6% to 90.5% of the population, and the deployment of 250/25 Mbps dramatically increased from 58.3% to 85.6% of the population. While deployment in rural areas and on Tribal lands lags behind deployment in urban areas at all five speed tiers, but the data show year-over year improvements for all speeds in these areas. For example, the deployment of 250/25 Mbps increased from 28.2% to 51.6% of the rural population
While fiber is the fastest home internet option by far, availability is still scattered. Due to the high cost of installing fiber service directly to homes, even major cities are still predominantly served by cable. Chicago, for example, only has 21% fiber availability as of 2020. Dallas has about 61% — and that’s actually high availability compared to other major metros in the US.
Image: CBS News
Challenges and Impact of inequitable distribution of broadband connectivity
Communities without reliable high-speed internet service cite a growing gap between the availability of resources and opportunities to their residents compared to those in communities that have a robust network. Given the ubiquitous nature of internet access, its vastly important to recognize how denial of broadband internet access, whether intentional or unintentional has become a severely debilitating factor for people and communities. Recognizing the importance of broadband and responding to such frustrations, states, communities and even individual people are seeking to close this gap. Most states have established programs to expand broadband access to communities that lack broadband internet connectivity or are undeserved. State efforts to expand broadband access are primarily focused on extending wired and fixed wireless infrastructure to the last mile: homes and small businesses. While Internet service providers, generally private companies licensed to distribute wireless and wired connectivity services have delivered reliable high-speed internet to households in most urban and suburban areas, many rural areas and areas with less population density remain under-served or lack services altogether. The issue of under-serving is particularly complex because people and regulators have used different definitions and standards from time to time. The challenge of closing the last-mile gap is compounded by geography, demographics, and the numbers and types of entities that provide service. In some states and regions, these patterns have led to uneven deployment of broadband infrastructure. While one rural community may have “fiber to the home and to the farm and to the cabin” provided by a local telephone company or cooperative, a neighboring community may lack the same level of broadband access.
While the Federal Government owns or manages key assets that support telecommunications infrastructure, the bulk of America’s telecommunications infrastructure is owned and managed by private-sector companies. This private market is a significant asset to our Nation’s economy and has helped the United States innovate and lead the world in each wave of telecommunications technology. Over the past several decades, Federal partnerships have been especially important for deployment in high-cost rural areas, where the unique challenges of geography, population density, and deployment costs may make it unprofitable to expand or operate networks – creating significant gaps in rural broadband coverage.
There are a unique set of challenges associated with delivering high-speed broadband to rural locations that service providers do not encounter in more urban locations, including geographical variables and high costs. Fortunately, recent fixed wireless solutions are equipped to address these variables as they serve as a cost-effective alternative to drop, distribution and/or feeder fiber, providing a whole new set of deployment models to the traditional Fiber-to-the-x (FTTx) deployment models. Unlike “urban jungles,” rural areas have a varying degree of terrain. Depending on the geography of the region, providers can encounter anything from rock and sand to compacted dirt and mud — making planning and executing a fiber buildout difficult. Many times, technicians are unaware of what type of soil composition they will be digging into until the project has begun. And then, they may find that getting the adequate trenches dug to lay the fiber is near impossible
According to a Fortune Article, Wealthier communities are two to three times more likely to have more than two choices for broadband providers than are communities with lower-than-average household incomes. With limited competition, it is perhaps unsurprising that Americans pay the second-highest broadband prices among OECD countries. Yet when new competition is introduced in broadband markets, the benefits are demonstrable. Look no further than Kansas City, Kan.; Chattanooga, Tenn.; Wilson, N.C.; and Longmont, Colo. for evidence that competition from a private or municipal broadband provider results in incumbent providers dropping prices and increasing speeds—but not in nearby areas the new competition didn’t serve.
Internet Availability and Affordability exacerbated in the Covid-19 era
Families across America, especially in semi-urban and rural areas often have to contend with throttled internet speeds. During Covid-19 as many families were forced to stay at home and do most of their activities at home, the demand for internet bandwidth has cast strains on the internet service providers’ ability as well as the rising data bills for many families.
Most families are hit by both the availability and affordability aspect. Contending with throttled internet speeds, many families often drives miles to find a spot where they can stream videos for work and class, including parking in acquaintances’ driveways to connect to Wi-Fi or a public utility like libraries or near a cellular tower across town.
The public health crisis has exposed New York’s digital divide. Lawmakers representing communities in upstate New York have voiced concerns about the issue for years, fighting to increase access to high-speed internet in rural communities that often struggle to even get a bar of cell service. But despite repeated pledges by state officials to remedy the situation, access to high-speed broadband internet remains elusive in the state’s bucolic areas.

“I would say that this current pandemic has really brought to light the challenges facing rural America when it comes to the lack of broadband,” said U.S. Rep. Anthony Brindisi, a Democrat whose district includes Utica and Binghamton. “These are challenges that many of us have been screaming about for many years, but [now] it seems to be very visible to the public at large.”
According to state Sen. Jen Metzger, a Democrat who represents a largely rural district in the Hudson Valley and Catskills., “There are many households that simply can’t afford it, and so we’re essentially reinforcing cycles of poverty and making it difficult for young people to realize their full potential in school and beyond,”
According to a Politico Article, Gov. Andrew Cuomo committed to providing broadband access to every New Yorker by the end of 2018, but missed the deadline. The percentage of New York residents and businesses served by “wired or wireless broadband” has gone from 70 percent in 2015, when Cuomo announced his program, to 98 percent, according to Department of Public Service spokesperson Jim Denn. According to David Little, executive director of the Rural Schools Association. “There’s vast stretches of land outside of urban areas that don’t have it, and so you have thousands of students sitting outside school buses being used as Wi-Fi hotspots so students could have some access closer to home.”
Teachers throughout the state have come up with creative solutions to help their students, including shipping out paper packets with assignments that students then mail back and calling students on landlines to assist with homework.
But for the most part, the coronavirus pandemic has frustrated families who have been calling for improved access for years.
Joanne Mazzotte, a counselor for the Crown Point Central School District in Essex County, said she hopes broadband is recognized as a basic necessity after the pandemic because of the struggles her family and others have faced. Cellular service in the area is so bad that to upload a file to Google Drive, “We’d have to huddle around one window and it would still take half an hour” despite living on a main road, she said.
How to get the Internet Service Providers to act
According to Industry estimates, based on variables like pole mounted or buried cables, laying fiber infrastructure can cost between $18,000 and $22,000 per mile. It’s all about return on investment (how quickly can the company get its cash investment back in order to reinvest in additional projects), and ability to grow the company.
Let’s look at a simple example with the following assumptions:
- $20,000 per mile for fiber infrastructure cost
- $600 per home to deliver service from the street
- 13 homes per mile (typical service area may have between 10 and 15)
- Average monthly cost for the provider to actually deliver the service after installation is $32 per month
- The subscriber pays on an average $65 per month for the service
- Net revenue per home is $33 per home
For a one mile build with 13 homes, the total project cost would be $20,000 PLUS the $600 for each home that connected to the service, about $2,140 per home – assuming that every home took service. If only 7 of those homes sign up for service, the cost per home served jumps to $3,460. By dividing the cost per home by the net revenue per home of $33, its simple to see that it will take nearly nine years for the provider to break even on the investment.
In case of multiple occupancy buildings, on average, fiber optic cable installation costs $1 to $6 per foot depending on the fiber count. It’s very difficult to estimate an exact price for an entire building to be wired, however an example would be $15,000 to $30,000 for a building with 100 to 200 drops. Fiber optic cabling is somewhat more expensive up front than copper cabling, but the greater capacity and reliability of fiber can actually reduce long-term costs.
It has been shown that States and local government bodies can use multiple policy levers to drive Internet Service Providers to expand broadband access, and some of these actions do not have to be dependent on available funding. States often support private enterprise broadband deployment through various means. In addition, where the Internet Service Providers fail to react, the state governments reserve the right to bring in non-profit cooperatives and special focus groups to build the necessary infrastructure.
- Grants and loans to service providers: States provide support, primarily through grants, to facilitate broadband deployment in un-served and under-served areas. Several states, including Minnesota and Tennessee, have funded their broadband expansion programs through appropriations, while others, including California and Colorado, have re-purposed funds that have traditionally supported universal telephone service.
- Identifying, setting up and promoting nonprofit utility cooperatives, and local governments to help make projects economically viable. In Minnesota, The Governor’s Task Force on Broadband, formed in 2011, provides a forum for stakeholders to study and discuss issues related to broadband. The Office of Broadband Development, Minnesota aims to connect all homes and businesses at speeds of at least 25 Mbps/3 Mbps by 2022 and 100 Mbps/20 Mbps by 2026 and become a national and international leader. West Virginia has passed several bills to encourage broadband expansion. In 2017, the Legislature passed a measure that established a goal of providing broadband access statewide, allowed the formation of cooperatives to provide the service, created a loan guarantee program to reduce risk for commercial lenders, and allowed Internet Service Providers to use micro-trenching technology to install infrastructure. In Maine, Maine’s ConnectME Authority, established in 2006 through the Advanced Technology Infrastructure Act, provides planning and infrastructure grants to facilitate broadband deployment to un-served and under-served communities. Between 2016 and 2018, ConnectME funded 14 planning grants totaling $451,000. Planning grants also help prepare applicants for ConnectME infrastructure grants. Between 2006 and 2018, ConnectME funded 144 infrastructure projects, providing more than $12 million to bring broadband infrastructure to nearly 40,000 households. In 2015, North Carolina’s Legislature tasked its Broadband Infrastructure Office (BIO), within the North Carolina Department of Information Technology, with developing a state broadband plan.
The universal service Schools and Libraries Program, commonly known as “E-rate,” provides discounts of up to 90 percent to help eligible schools and libraries in the United States obtain affordable telecommunications and internet access. The program is intended to ensure that schools and libraries have access to affordable telecommunications and information services.
There are currently 331 municipal networks in operation today in the U.S. We reviewed every state that has roadblocks preventing the establishment of municipal networks and compared them to states that do not have such restrictions in place. What we found was that states without restrictions enjoyed higher access to low-priced broadband plans on average.
According to a 2019 report on the health of municipal broadband, 22 states now have substantive roadblocks to establishing municipal networks to residents, down from last year’s 25. Three more states, Arkansas, California and Connecticut now permit such municipal broadband networks in full. Residents in states with no roadblocks or restrictions in place against municipal broadband have, on average, 10% greater access to low-price broadband (which we classify as any standalone internet plan $60 per month or less).
Many industry insiders feel that with the Covid-19 crisis, the focus is shifting to correct the systemic imbalances that have existed and that were confabulated or bloated due to decades of mismanagement and allowing private internet service providers to have a free rein. There’s absolutely no reason that people living in rural areas or Indian country and folks living in under-served areas must leave the safety and comfort of their homes and sit in a car outside of school or library in order to do the things that people in more than 90% of United States take for granted, that is, being able to access reasonable broadband internet from home. Further, now with Covid-19, telehealth is being used for primary care visits. The patient can stay at home and connect to their primary care provider via the internet. That way people don’t have to risk the face-to-face interaction. And so if there’s a silver lining to all of this, maybe this crisis, this pandemic, is bringing these issues to the forefront. And saying, look, there is no reason that people living in certain parts of country need to deal with essentially what is third-world connectivity.
In terms of funding to support tele-health implementation, now with Covid-19, the FCC has $200 million available to help hospitals and clinics to provide services to patients in their homes. Under the program, healthcare entities would have internet service providers bid on service improvements, such as laying fiber to a hospital or clinic, and then the funds would cover up to 65 percent of the costs of the service improvements.
One way to make sure internet gets to everyone is to make the internet a utility. It has to be free and open and available to everyone, everywhere, every time. All of the rural under-served and not served areas and Indian country needs broadband. All of these areas and communities need additional spectrum to do what they need to do. Everything ranging from tele-health to the new innovations that are taking place is denied to people where there is lack of adequate broadband capabilities.
Much has been written about the digital divide and its impact on those with limited access to broadband Internet service. Broadband Internet service has become a cornerstone to the world economy, as many things including advertising, sales, news, education, job applications, and basic communication move predominantly online. Those with broadband Internet tend to have an advantage over those without, and the people least likely to have broadband access live in rural areas. Unless broadband access is addressed in rural areas, today’s disadvantages resulting from limited broadband access will continue to grow in prominence as bandwidth needs expand and the broadband definition changes in the future. There’s always existed this lack of parity in telecommunications between rural and urban areas and from the beginning of federal communications laws in 1934, the FCC was created precisely to address a lack of access in more rural and remote areas. And so its time for everyone, the FCC, private telecom companies and local and state governments to embrace this principle called universal service, the idea that all Americans would have access to communications services.

This is part II of our blog post on Exposure Notification. Our original blog on Exposure Notification was published August 30th.
Let’s look at the Background
Public Health Agencies around the world and especially in US have had little success with using mobile phones based technology to monitor the spread of Coronavirus and to warn users proactively.
Some public health agencies in the United States and around the world wanted to build mobile apps that would help them track the spread of the virus, through a process known as “contact tracing.” Due to the slow moving government apparatus, legal and procedural requirements and the logistical challenges, few of such program could take off. The contact-tracing apps that were initially launched did not function properly because of certain limitations, primarily the concerns around privacy and collection of data.
Apple and Google announced a surprise partnership at the start of this pandemic in April. When Apple and Google announced their work together on the COVID-19 Exposure Notification API, the companies put behind years of rivalry to join hands to help people and Public Health Authorities fight this massive battle. Apple and Google announced two phases of the Contact Tracing project. During the first phase, which is what came with iOS 13.5, laid out that that users first download an app from their public health authority and then opt-in to Exposure Notifications. The process of Exposure Notification System works through sharing anonymous Bluetooth beacons with nearby devices running the same software, tagging those that suggest extended and close contact associated with coronavirus spread, and saving the last 14 days of these records.
At the same time, Apple and Google also indicated start of work on the second phase, which would reduce the reliance on contact tracing app from public health authorities while bringing the core functions of the COVID-19 Exposure Notification technology directly into iOS and Android. This is essentially what Apple and Google announced on Tuesday, 1st September.

So what is new in the second phase of Exposure Notifications
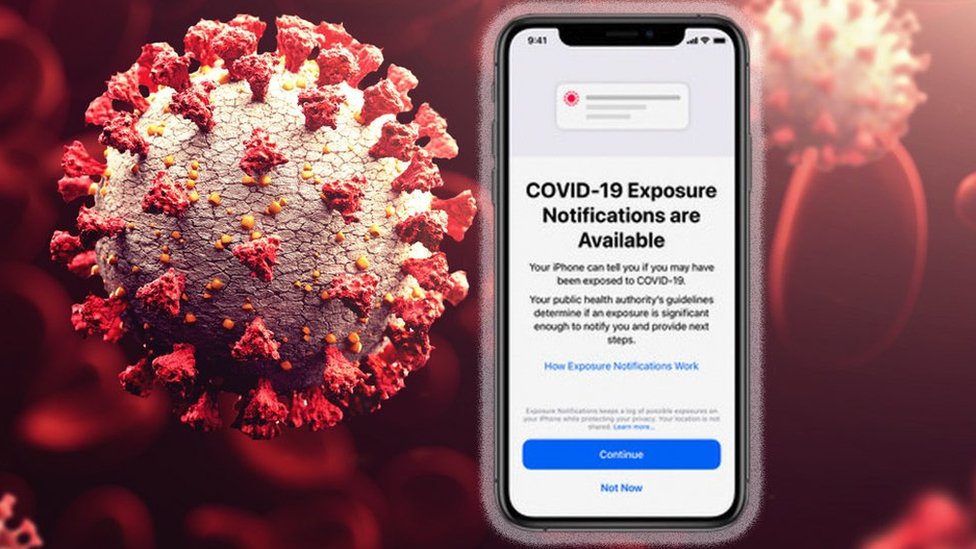
Apple and Google announced on 01st September that their joint program, contact tracing Exposure Notifications System, can inform people of potential exposure to COVID-19 without a dedicated Exposure Notifications app. The second phase of this program, the companies announced, re-launches the warning software in a new and better Avatar, so that state public health agencies can participate without having to create customized apps. This app-less functionality is called Exposure Notifications Express and is only available when a Public Health Authority (PHA) supports it.
The two partners, Apple and Google are introducing new tools that benefit both the public and public health authorities, making it much easier for public health authorities to implement digital exposure notification, while reducing a step in the process for the general users. For public health authorities, now they do not need to worry about the need for developing and maintaining their own individual contact tracing application. Apple made this breakthrough via the iOS 13.7 system update, released 01st September to general public, while Google is implementing it with an automatically generated application on Android 6.0, upcoming later in September, taking a little longer because of the very different method through which it manages system services and OS updates.
For public health authorities, the new changes bring significant ease of operation as the process of adopting Exposure Notifications Express by users is significantly streamlined compared to adopting the existing Exposure Notification API where users first had to download the contact tracing application. Public health authorities simply provide a configuration file that includes their name, logo, criteria for triggering an exposure notification, and information and protocol that is displayed to users following an exposure. The existing way of Exposure Notification API demanded that users download the contact tracing application from their public health authority first before proceeding with other steps. This was a major headache for public health organizations who were required to maintain their own infrastructure and software application. Further it was an additional and often confusing step for users. Now that part is completely eliminated benefiting both public health authorities and users.
Further Apple and Google say that they will use the information provided by the public health authorities to offer a fully operational Exposure Notification Systems on behalf of the public health authority directly integrated into their respective operating systems, in case of Apple this is iOS 13.7.
Crucially, Public health authorities still have full control over the system, though, and there are no additional privacy or data related concerns. The Public Health Authorities still dictate and control the process of triggering notifications, what is the language and structure of the advice, and guidance on the next course of action for exposed individuals.

iOS 13.7 changes
With the new Exposure Notification Express, which forms the second phase of Exposure Notification System, the system removes one of the key barriers to adoption that led to a slow start to the software. Once users update iOS 13.7, users can now enable COVID-19 Exposure Notifications directly in the Settings app on their iPhone. This new process is called Exposure Notifications Express. The process is as simple as enabling user preferences in any other application and just takes a few taps, including agreeing to the public health agency terms and conditions of service. Additionally, users will also be able to opt-in to receive a push notification when their local public health authority adopts Exposure Notifications Express.
Once an user enables exposure notifications in the Settings, their iPhone will begin monitoring with Bluetooth to log possible exposures so the user can be notified of a potential COVID-19 exposure based on the guidelines set by the local public health authority. The process of monitoring and triggering Exposure Notification System works without any changes, through sharing anonymous Bluetooth beacons with nearby devices running the same software, tagging those that suggest extended and close contact associated with coronavirus spread, and saving the last 14 days of these records.
At least in the United States, many people haven’t had the option of participating, as states have been slow to create apps. Now, with “exposure notifications express,” states will have less work to participate. Through this simplification pf approach, Apple and Google hope that adaption rate of the Exposure Notifications Express system will dramatically increase, at both levels, from users and public health authorities. The first public health authorities in the United States to adopt the Exposure Notification Express system will be Maryland, Nevada, Virginia, and Washington, D.C.
Users who live in states that participate in the software may get a pop-up notification, prompting them to opt into the program. By following simple steps, they can share their Bluetooth data and receive notifications if they come in contact with another participant who has tested positive. For states that already have a contact tracing application standalone application using the COVID-19 Exposure Notification API, those apps can still exist and operate on their own. As of right now, Apple and Google say that 25 states and territories, representing more than 55% of the population, are exploring Exposure Notifications System solutions.
Finally, Apple and Google emphasize that all of the original privacy protections of the Exposure Notification API also extend to the Exposure Notifications Express. Users must explicitly enable exposure notifications, nothing is enabled by default. No location data is shared and the system does not share your identity with other users, Apple, or Google. All matching is done on-device and users have full control over whether they want to report a positive test.
“I would say this is an improvement,” said Jeffrey Kahn, director of the Johns Hopkins Berman Institute of Bioethics. Kahn, who has been studying the use of technology to fight the virus, said states have been hamstrung by indecision around which technology vendors they should use to build their apps, among other issues. He said this may help speed up adoption, but shouldn’t be considered a magic bullet.
“Public health agencies are carrying an extraordinary load in managing the novel coronavirus response,” said Scott J. Becker, head of the Association of Public Health Laboratories, in a statement provided by the companies. “The easier we make it for state and territorial public health agencies to develop and deploy, the sooner we can expand COVID-19 exposure notification in our communities and help end the pandemic.”
]]>
Whenever there is a talk of infusing technology, automation and intelligence in to tasks or processes, the solutions proposed fall in to two broad buckets. The first is the conventional use of the term Artificial intelligence, machine learning, deep learning and cognitive learning, which typically work outside human intervention and are largely driven by some kind of an algorithm to achieve its goal. The handling of regular transactions as well as any exceptions are defined within the AI program and the machine doing the job in case of touch and feel jobs like manufacturing or the algorithm producing the result in case of purely online work. The second category is where Artificial Intelligence is applied to work in conjunction with the humans and human intervention and interaction is a critical part of the successful completion of the job. This second type is known as Augmented intelligence or Augmented reality.
Another way of looking at what happens with augmented and artificial intelligence is the degree to which algorithms and the programs running the physical machines are expected to make decisions on their own. Is the decision making assisted by humans, controlled by humans or completely out of control of humans?
It’s critical to note that while the technologies and fundamentals powering both Artificial intelligence and Augmented intelligence are largely the same, the applications, goals and objectives are objectively different. Simply put, AI creates a human less environment while Augmented Intelligence or Intelligence Augmented as it’s often called, seeks to create an environment for betterment of humans and human endeavors.
There’s virtually no major industry where modern AI — more specifically, “narrow AI,” which performs objective functions using data-trained models and often falls into the categories of deep learning or machine learning — hasn’t already affected. That’s especially true in the past few years, as data collection and analysis has ramped up considerably thanks to robust IoT connectivity, the proliferation of connected devices and ever-speedier computer processing.
- In Manufacturing: AI powered robots work alongside humans to perform a limited range of tasks like assembly and stacking, and predictive analysis sensors keep equipment running smoothly.
- Healthcare: In the comparatively AI-nascent field of healthcare, diseases are more quickly and accurately diagnosed, drug discovery is sped up and streamlined, virtual nursing assistants monitor patients and big data analysis helps to create a more personalized patient experience.
- Education: Textbooks are digitized with the help of AI, early-stage virtual tutors assist human instructors and facial analysis gauges the emotions of students to help determine who’s struggling or bored and better tailor the experience to their individual needs.
- Media: Journalism is harnessing AI, too, and will continue to benefit from it. Bloomberg uses Cyborg technology to help make quick sense of complex financial reports. The Associated Press employs the natural language abilities of Automated Insights to produce 3,700 earning reports stories per year — nearly four times more than in the recent past.
- Customer Service: Last but hardly least, Google is working on an AI assistant that can place human-like calls to make appointments at, say, your neighborhood hair salon. In addition to words, the system understands context and nuance.
Source: McKinsey & Company
According to a recent publication, of the 9,100 patents received by IBM inventors in 2018, 1,600 (or nearly 18 percent) were AI-related. Here’s another: Tesla founder and tech titan Elon Musk recently donated $10 million to fund ongoing research at the non-profit research company OpenAI — a mere drop in the proverbial bucket if his $1 billion co-pledge in 2015 is any indication. And in 2017, Russian president Vladimir Putin told school children that “Whoever becomes the leader in this sphere [AI] will become the ruler of the world.” He then tossed his head back and laughed maniacally.
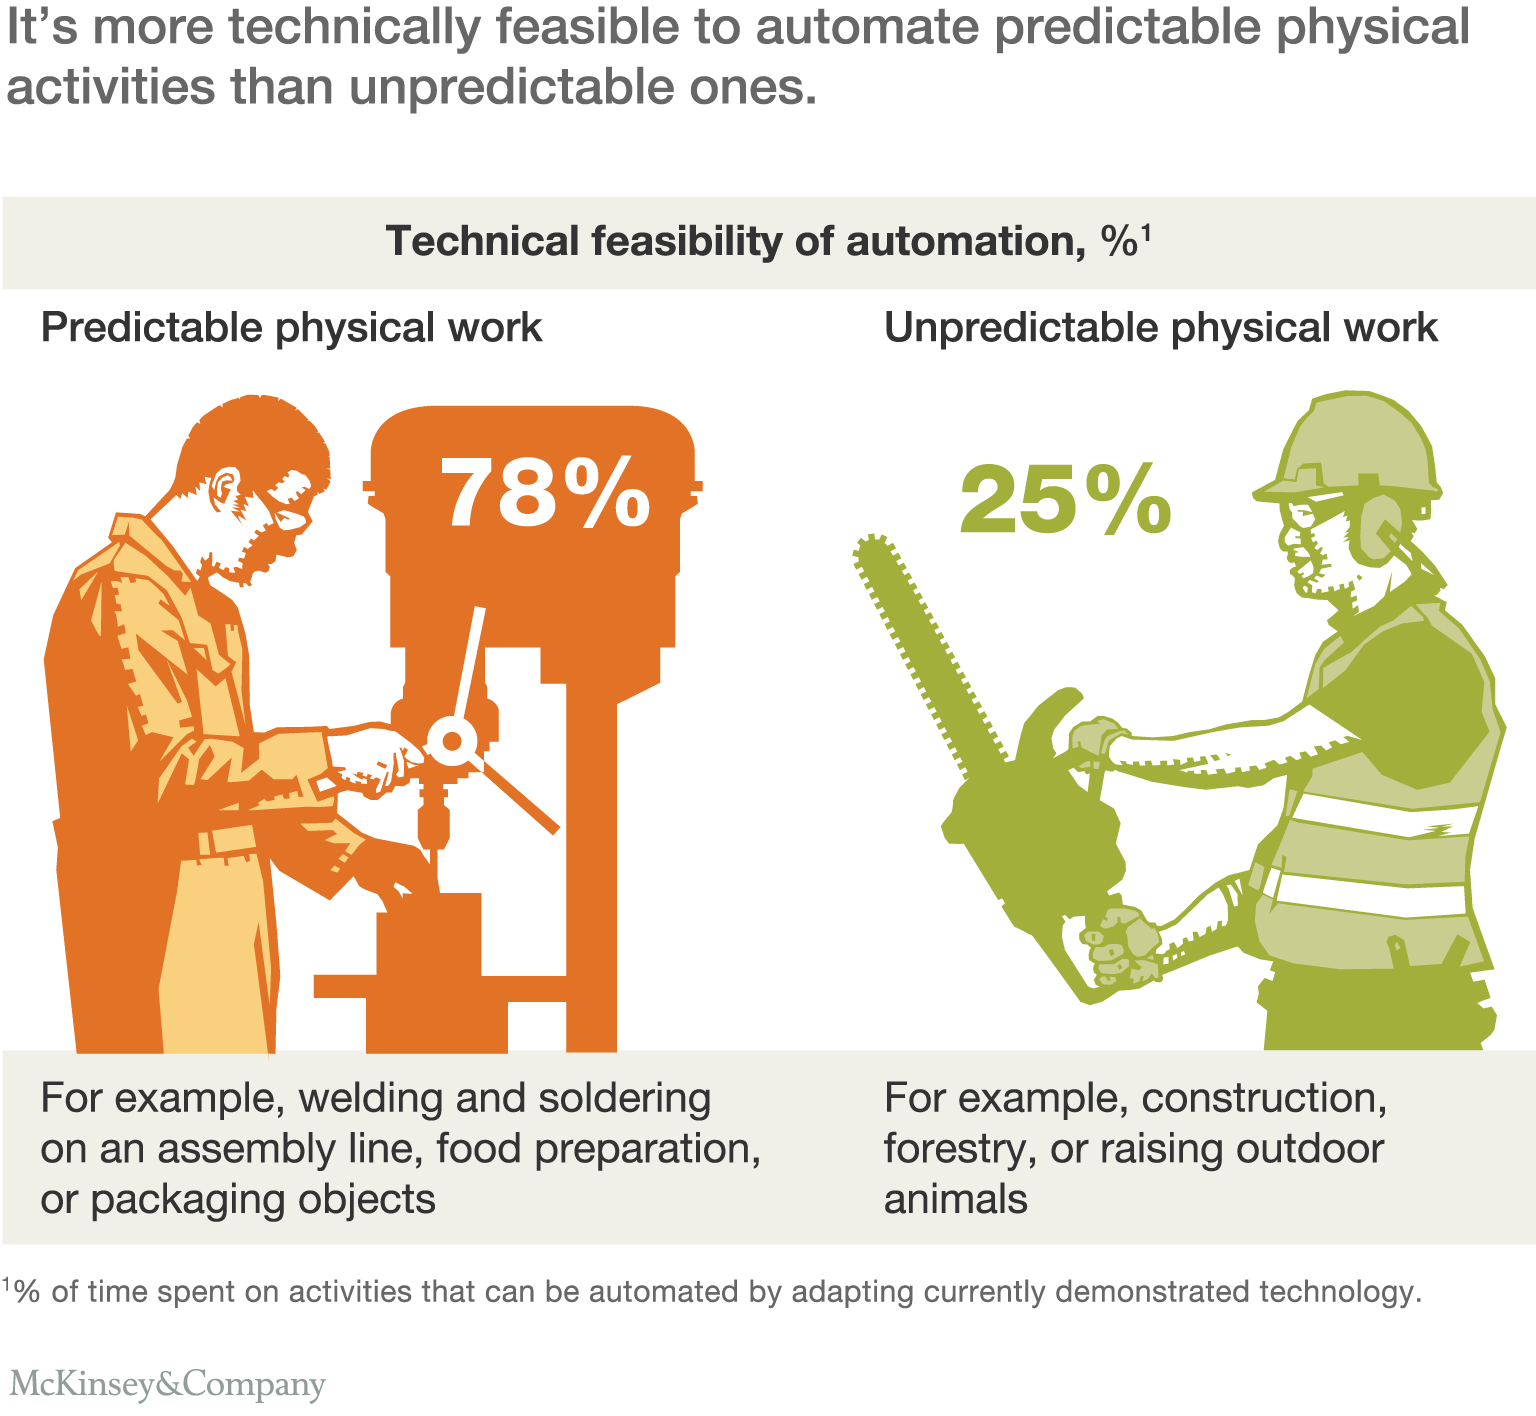
The single biggest strength of Artificial intelligence is the simple fact that it can do repetitive tasks better than anything else. And the more quantitative, the more objective the job is—separating things into bins, washing dishes, picking fruits and answering customer service calls—those are very much scripted tasks that are repetitive and routine in nature. In the matter of five, 10 or 15 years, they will be displaced by AI.
Yet even the most pragmatic AI scientists stress that today’s AI is useless in two significant ways: it has no creativity and no capacity for compassion or love. Rather, it’s “a tool to amplify human creativity.” In other words, sure you can teach AI to make strokes with a brush in a canvas, but an AI driven machine can never in a million years paint a Monalisa.
The most advanced robot costing many millions in research dollars and years of work, cannot pickup a tea cup like a 2 year old can. Or millions of sensors on a robot cannot feel taste and smell like humans do. Sure a robot Make millions of calculations in a second, which is many hundreds of times more than the most intelligent human can, sure a robot can discern each smell, or can break down each material in to its atoms and sub-atoms, but it cannot experience the same thoughts, emotions and feelings that human brain can.
The second biggest fear around AI stems from the AI and machine learning applications inheriting some of the human biases based on pre-disposed notions and behaviors that humans may code in to or indirectly influence the program.
Augmented Intelligence on the other hand doesn’t replace humans with technology rather uses Artificial intelligence to aid humans in doing a job.
In recent years, in AI technology rankings in terms of the value they create for businesses, Augmented Intelligence was ranked in second place, just below virtual agents. However, Gartner predicts that “Decision support and AI augmentation will surpass all other types of AI initiatives” creeping into first place this year and then exploding as we reach 2025 becoming around twice as valuable as virtual agents.
Just like regular project management work, any organization looking to employ AI needs to first define its use cases and requirements clearly and describe the Big Y, or the big problem it’s trying to solve. Then, they need to define the various aspects of business goals, or the product that they want to build. The next step is to outline data requirements and functionality to solve those business goals. And finally, what’s the ROI or returns the organizations expects. What makes AI and machine or cognitive learning projects unique is that they also need to consider the human-machine dynamic. For example, which part of the chain or which components of the product or solution do they want to hand over entirely to machines to execute, and which parts do they want to retain for their Human Resources? Where machine or a computer algorithm based program is making the decision, is it completely autonomous or is there a human there to monitor? Is The machine or computer program Only responsible to feed data, information or half finished product to human to make the final decisions? In the scope of these decisions, then, it makes a lot more sense to create an AI role matrix which can evolve over time. This matrix Lays down specifically the kind of role AI or cognitive learning system will play for that particular function or process.
Source: USM Business Systems
Getting to true autonomous intelligence or fully independent, cognitive learning powered AI model is proving to be real difficult. Even one single instance of non-compliance or faulty decision making can throw the entire program off tracks.
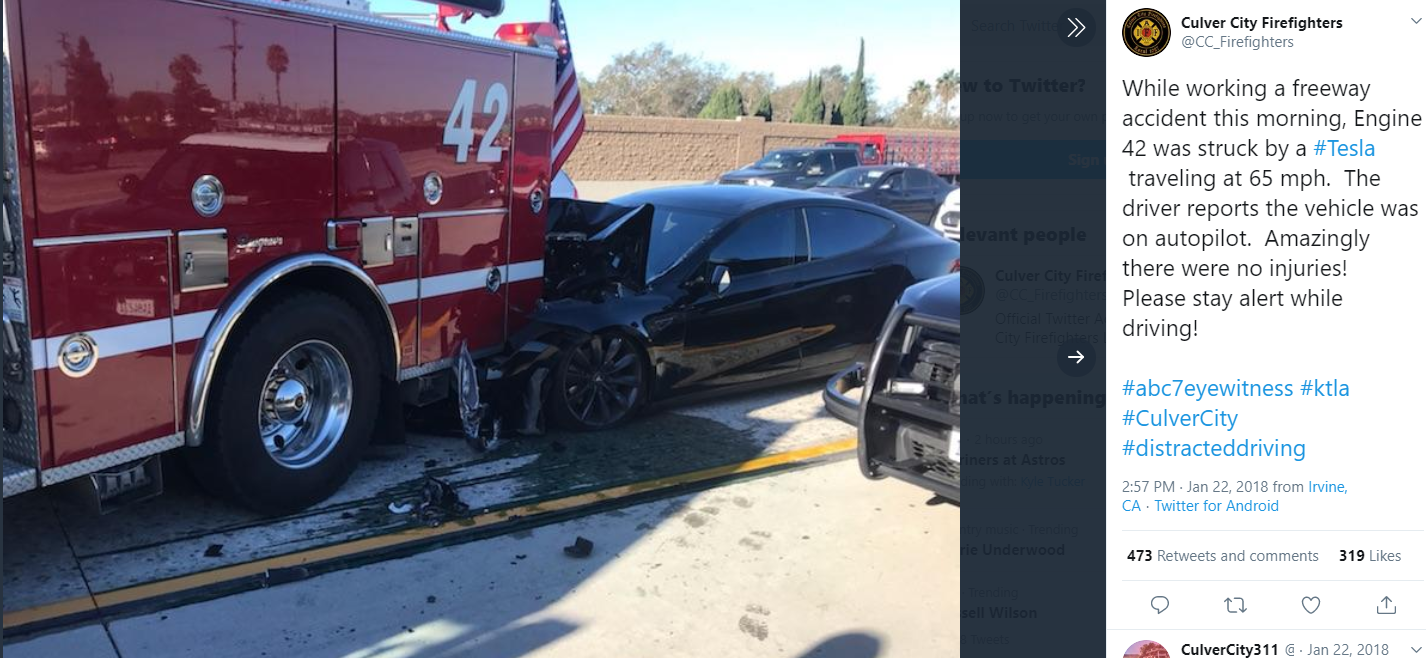
During Tesla’s 2019 Autonomy Day, Tesla CEO Elon Musk said the company is expected to have one million vehicles on the road by the end of 2020 that could function as robotaxis. Though the semi-autonomous Autopilot and Full Self-Driving, or FSD, features are loved by some, others say Musk’s driverless dream is far from becoming a reality. Despite many hundreds of millions in investment and almost a decade of efforts, Tesla’s fully autonomous driving mode is not fully autonomous anymore rather in the best-case scenario is now only viewed as a partial augmented driving mode. In other words, human driver has to control the inputs. And while some of the Tesla’s self-driving features are loved by some, many still view it as unfit for our roads. While the hype around the autonomous driving mode was skyrocketing, and just as Tesla started charging a hefty premium for their self-driving feature, a handful of incidents and accidents changed all that. Scenarios of false-positives, or false-negatives, which are built in to the algorithms powering the programs behind the autonomous driving software, lead to further complications of their own, creating as many problems as they solve. In the best-case scenario, public confidence in self-driving technology is still many years if not decades away.
Source: ABC News
Watching the Youtube training sessions posted by Waymo, the Alphabet subsidiary in charge of self-driving cars, reveals the concerns with self-driving technology. One video shows a car that repeatedly and without reason stops in the middle of a street and then drives off again. The explanation came from a passer-by who was carrying a STOP sign sticking out of his bag, misleading the vehicle. In other words, the machine can drive itself, but it lacks the ability to differentiate ‘stop’ signal in different contexts and nuances of incidents on public roads.
The loan underwriters at top banks quickly realized that leaving decision making with a compute program is a recipe for disaster as the program has inbuilt biases and no amount of learning can make the program foolproof. Hence in most cases, AI programs are only limited to the first few stages in the process while the critics decision is made by a human.
Similarly, Apple credit cards have recently discriminated against women,giving them 50% less credit than men with the same income and profile.
Let’s use Netflix as an example. Say you recently watched “Orange is the New Black.” Netflix may then suggest other shows with prison themes, or documentaries about life behind bars, or shows with a strong female lead, etc.
Based on past data (your recently watched shows and movies), it’s able to make a prediction about what you will want to watch next. Once you make your latest selection, it will adjust its algorithm to further customize your experience.
According to a 2017 scholarly article on Augmented intelligence by Researchers Zheng and Wang, Within augmented intelligence, researchers Define models according to the varied degree of AI and human influence.
- The first classification is called Human-in-the-loop hybrid-augmented intelligence) Human-in-the-loop (HITL) hybrid-augmented intelligence is defined as an intelligent model that requires human interaction. In this type of intelligent system, human is always part of the system and consequently influences the outcome in such a way that human gives further judgment if a low confident result is given by a computer. HITL hybrid-augmented intelligence also readily allows for addressing problems and requirements that may not be easily trained or classified by machine learning.
- The second classification looks at (Cognitive computing based hybrid-augmented intelligence) In general, cognitive computing (CC) based hybrid-augmented intelligence refers to new software and/or hardware that mimics the function of the human brain and improves computer’s capabilities of perception, reasoning, and decision-making. In that sense, CC based hybrid-augmented intelligence is a new framework of computing with the goal of more accurate models of how the human brain/mind senses, reasons, and responds to stimulus, especially how to build causal models, intuitive reasoning models, and associative memories in an intelligent system.
Augmented intelligence follows a five-function cadence that allows it to learn with human influence. It repeats a cycle of understanding, interpretation, reasoning, learning, and assurance. Here’s how it works:
- Understanding: Systems are fed data, which it breaks down and derives meaning from.
- Interpretation: New data is inputted; the system then reflects on old data to interpret new data sets.
- Reasoning: The system creates “output” or “results” for new data set.
- Learn: Humans give feedback on output and the system adjusts accordingly.
- Assure: Security and compliance are ensured using blockchain or AI technology.
Source: Global Data Magazine
It is clear and evident that AI is here to stay. Humans have a deep reliance on Artificial Intelligence which has been around for decades. Yet, the future of Artificial Intelligence is brightest with the humans, morphing in to Augmented Intelligence. Having humans and machines work hand-in-hand is a win-win for both parties.
Most scientists and researchers agree that its probably extremely implausible, if not impossible to imagine collective human failure to the extent that AI is allowed to grow unchecked, while simultaneously all other uses of AI beneficial to humankind are ignored.
One thing is certain though: despite the ominous predictions and warnings on doomsday scenarios, arising out of the impact of AI on humanity and society, AI will never take over the world or morph in to Terminator style Machines Or Will Smith’s I robot kind of intelligence.
]]>